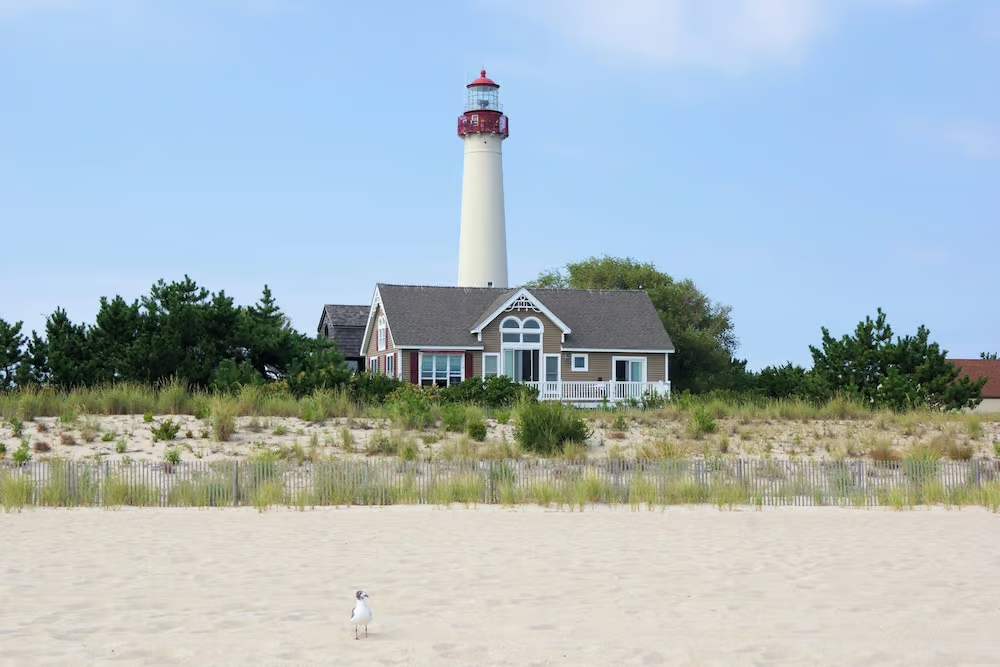
The pros, cons, financing considerations, and best beach towns for Washington, DC-area buyers
There’s something appealing about having a place at the beach that’s truly yours. No searching for summer rentals, no packing quite as much for every trip, and the flexibility to head out of town whenever your schedule allows.
For many people living in Washington, DC, Alexandria, Arlington, and the surrounding area, buying a beach house is a long-term goal. And sometimes, the greatest value has nothing to do with the property itself: it’s the people you meet, the traditions you create, and the community that becomes part of your life.
But owning a vacation home comes with responsibilities and expenses that are easy to underestimate. And choosing the right location involves more than finding a beautiful house near the water.
Whether you’re considering the Delaware beaches, Ocean City, the Outer Banks, or a waterfront property along the Chesapeake Bay, here’s what to think about before buying a second home.
Is Buying a Beach House Worth It?
The answer depends on how you’ll use it, what you can comfortably afford, and what you want out of the experience.
A beach house can be a wonderful lifestyle purchase. It may also become a long-term asset or eventually serve as a retirement home (read more in our guide on What to Know About Owning Multiple Properties in Retirement). But we encourage buyers to think about the lifestyle benefits first rather than assuming the property will be a great financial investment.
The Benefits of Owning a Beach House
- More time away without the planning. When you own a beach house, you can decide to spend a weekend there without researching rentals or booking months in advance.
- A familiar place for family and friends. Over time, a second home can become the setting for summer traditions, holidays, and visits with friends and extended family.
- The opportunity to enjoy different seasons. Beach towns aren’t just for summer. Fall weekends, spring getaways, and quieter winter visits can be some of the best times to enjoy the coast.
- Potential rental income. Depending on the property and local regulations, renting your beach house when you’re not using it may help offset some ownership expenses.
- Long-term flexibility. Some buyers eventually transition their vacation property into a primary residence, particularly as they approach retirement or begin spending more time away from the city.
The Part You Can’t Put a Price Tag On
Some of the greatest benefits of owning a beach house are almost impossible to calculate: the friendships, traditions, and sense of community you build by returning to the same place year after year.
For our family, Bethany Beach has been much more than a vacation destination. In fact, if my family hadn’t bought our beach house, I might never have met my husband, Doug, who worked as a Bethany Beach lifeguard during college!
Not every beach house purchase leads to meeting your future spouse, of course. But you never know which relationships, memories, and experiences will come from having a place that brings you back year after year. Those are the returns you’ll never find on a spreadsheet.
The Drawbacks of Owning a Beach House
- You’re maintaining two homes. In addition to your primary residence, you’ll have another property to clean, furnish, insure, repair, and manage.
- Coastal maintenance can be expensive. Salt air, moisture, wind, and storms can accelerate wear on exterior materials, windows, decks, HVAC systems, and other components.
- Insurance can be complicated. Coastal properties may have significant flood, wind, or storm-related risks, and coverage can be more expensive or restrictive than buyers expect.
- You may feel obligated to go there. This is an underrated consideration. Some owners love returning to the same place every weekend. Others eventually realize they miss traveling to different destinations.
- Rental income isn’t guaranteed. If you’re counting on rental revenue, you’ll need to account for seasonality, management fees, repairs, vacancies, and local regulations.
The best purchase is one you can enjoy and afford even if appreciation or rental income doesn’t meet your expectations.
How Does Financing a Beach House Work?
How you intend to use the property can affect your financing options. A home purchased primarily for personal vacations may qualify for different terms than one purchased primarily to generate rental income.
Second-Home Loans vs. Investment-Property Loans
For eligible buyers, conventional second-home financing may offer lower down payment requirements and more favorable pricing than investment-property financing. Some programs permit down payments of approximately 10%, although requirements depend on the borrower, property, and loan program. Lenders typically evaluate personal occupancy, rental arrangements, existing housing expenses, debt, income, credit, and reserves.
Investment-property financing generally has different underwriting requirements, potentially higher down payments and interest rates, and different rules for using rental income to qualify. Specialized programs may be available for certain short-term rental purchases.
What If You Plan to Rent the Home Occasionally?
Occasional rentals do not automatically determine a property’s loan classification. The intended use, rental and management arrangements, and specific loan guidelines all matter. Always accurately disclose your plans to your lender. Mortgage rules and tax rules are not necessarily the same, so discuss rental-related tax questions with a qualified tax adviser (you can also review our overview of the Tax Benefits of Homeownership).
Not All Lenders Offer the Same Programs
One of the most important things we tell buyers is not to make assumptions based on a general rule—or even one conversation with a lender. Different lenders offer different programs, and requirements for down payments, reserves, rental-income qualification, and eligible property types can vary. A program that isn’t a fit with one lender may not be the only available option. That doesn’t change the need to meet the applicable occupancy and underwriting rules.
We can help connect buyers with experienced mortgage professionals who understand second-home and investment-property financing so they can evaluate options suited to their goals.
Can You Use Equity in Your Current Home?
Some buyers use savings or investments for their down payment, while others explore a home equity loan or line of credit secured by their primary residence. Higher-priced properties may require jumbo financing, and certain banks offer portfolio programs. Each approach carries different costs and risks; borrowing against your primary home also increases debt secured by that property. Compare options carefully with your lender or financial adviser.
For more tips on the ins and outs of buying a second home, read our post: A Comprehensive Guide to Buying a Vacation Property
What Does It Really Cost to Own a Beach House?
The mortgage payment is only part of the equation. Before making an offer, calculate the full annual cost of ownership, including:
- Mortgage principal and interest
- Property taxes
- Homeowners, flood, and any additional wind or storm insurance
- HOA or condominium fees, if applicable
- Utilities, internet, and security systems
- Landscaping, pest control, and routine maintenance
- Seasonal opening and closing services
- Repairs and replacement reserves
- Property management or caretaker costs
- Travel expenses to and from the property
For coastal homes, we’d also pay particular attention to the age and condition of the roof, windows, exterior siding, decks, and HVAC systems.
If you’re purchasing a condominium or a home in an HOA, review the association’s financial health, reserves, insurance coverage, rental restrictions, and any anticipated special assessments. A house that looks affordable based on the mortgage alone may feel very different once you understand the full carrying costs.
Flood Insurance and Coastal Property Risks
This is one area where buyers should do their homework before making a purchase. Not every beach house is in a high-risk flood zone, but proximity to the coast creates risks that don’t always exist with inland properties.
Before buying, consider:
- Flood risk: Review the property’s FEMA flood designation, elevation information where available, and any known flooding history.
- Insurance availability and cost: Obtain actual quotes for the specific property before removing your insurance or financing contingencies.
- Storm exposure: Understand the home’s exposure to wind, storm surge, and heavy rain.
- Property condition: Have the home inspected by professionals familiar with coastal construction and maintenance issues.
- Long-term risks: Consider erosion, drainage, changing insurance costs, and how the surrounding area may be affected by future storms.
Remember that standard homeowners insurance generally does not cover flooding. Even properties outside designated high-risk flood zones can experience flood damage. You can begin researching a property’s flood risk through FEMA’s Flood Map Service Center and explore policy options via FloodSmart.gov (National Flood Insurance Program), while working with a local insurance professional to understand actual coverage and costs.
Should You Rent Out Your Beach House?
Renting your beach house can help offset expenses, but it’s important to understand the trade-offs. Before buying a property with rental income in mind, ask:
- Are short-term rentals permitted by the town, county, and HOA?
- Is a rental license or registration required?
- What lodging, occupancy, or other taxes apply?
- How much could the property realistically earn after expenses?
- Who will handle cleaning, maintenance, guest communications, and emergencies?
- How much personal use are you willing to give up during the most desirable rental weeks?
The last question is especially important. In many beach markets, the weeks when a property commands the highest rental rates are also the weeks you’ll most want to use it yourself. We recommend reviewing actual rental history when available and speaking with an experienced local property manager rather than relying entirely on projected income in a listing.
The Best Places to Buy a Beach House Near Washington, DC
For buyers living in Alexandria, Arlington, or Washington, DC, one of the biggest considerations is how often you’ll realistically make the trip. A destination that works beautifully for a two-week summer vacation may be less appealing if your goal is to drive there on Friday afternoons and return Sunday evenings. (Exploring coastal trips first? Check out our guide to Weekend Getaways from DC).
Here are several of the most popular options to consider:
Delaware Beaches: Rehoboth Beach, Bethany Beach, Lewes, and Fenwick Island
- Best for: Families and buyers who want an Atlantic beach destination within weekend-driving distance of DC.
The Delaware beaches are among the most natural choices for buyers in the Washington area. We know this market personally because our family owns a home in Bethany Beach, and one of the things we appreciate most is being able to enjoy the area beyond the traditional summer season. Each town offers something a little different:
- Rehoboth Beach is known for its boardwalk, restaurants, shopping, and lively atmosphere. It’s a great option for buyers who enjoy being able to walk to activities and dining.
- Bethany Beach has a quieter, more residential feel, with a smaller downtown and a strong tradition of family beach vacations.
- Lewes offers historic charm, restaurants, shops, and access to Delaware Bay beaches. It’s worth understanding the difference between bayfront and oceanfront locations when comparing properties.
- Fenwick Island offers another Atlantic beach option, with a quieter setting and convenient access to nearby Ocean City.
Travel times vary considerably based on where you live, when you leave, and summer traffic. A trip that feels easy on a weekday can take much longer on a busy Friday afternoon. For buyers who plan to use their beach house frequently, we think the Delaware coast is one of the best places to begin the search.
Ocean City, Maryland
- Best for: Buyers who want a lively beach environment, condominium options, and access to a large vacation rental market.
Ocean City offers miles of Atlantic coastline, a well-known boardwalk, restaurants, entertainment, and a wide variety of housing types. Buyers can explore everything from oceanfront condominiums to detached homes in quieter residential areas.
Because different sections of Ocean City have different atmospheres, it’s worth spending time exploring before choosing a location. Buyers considering rentals should pay particular attention to condominium and HOA restrictions, management expenses, and the property’s rental history. Nearby Assateague Island is a wonderful recreational destination, but it isn’t a conventional residential beach-house market.
The Outer Banks, North Carolina
- Best for: Buyers who prefer longer vacations, larger beach houses, and a more expansive coastal setting.
The Outer Banks offers a different experience from the Delaware and Maryland beaches. Communities such as Duck, Corolla, Southern Shores, Kitty Hawk, and Nags Head provide a range of residential settings, beach access, and vacation-home options.
The Outer Banks is generally a longer drive from the DC area, which may make it better suited to extended stays rather than frequent two-night weekends. Some areas also have greater exposure to coastal flooding, storms, and erosion, making property-specific due diligence particularly important. For buyers who envision spending several weeks at a time at the beach, rather than driving back and forth every weekend, the Outer Banks can be worth exploring.
Chesapeake Bay: Annapolis, St. Michaels, and Kent Island
- Best for: Buyers who prioritize boating, waterfront views, and access to the water over traditional ocean beach vacations.
The Chesapeake Bay offers a different type of second-home lifestyle:
- Annapolis combines waterfront living with restaurants, shopping, sailing, and a vibrant downtown.
- St. Michaels offers a smaller Eastern Shore setting with historic charm, boating, and a slower pace.
- Kent Island and Stevensville provide additional waterfront and water-access options, with convenient access to the Bay Bridge.
These destinations may be particularly appealing to buyers who want to spend weekends boating, kayaking, or enjoying waterfront restaurants. However, it’s important to distinguish Bay waterfront living from an Atlantic Ocean beach experience. Beach conditions, water access, and recreational opportunities vary significantly by location—and while some Bay destinations are closer to DC, summer traffic around the Bay Bridge can still be substantial.
How Far Is Too Far for a Beach House?
One of our biggest recommendations is to be realistic about the drive. Ask yourself how you actually plan to use the property. If you want to leave after work on Friday and return Sunday evening, convenience may be more important than finding the largest or most impressive home. If you plan to spend most of July or August at the beach, a longer drive may be much less of an issue.
It’s also worth visiting your preferred destination outside peak summer season. You’ll get a better sense of which restaurants and businesses remain open, what the community feels like year-round, and whether you enjoy the area when it isn’t full of vacationers.
Should You Buy a Beach House Now or Keep Renting?
Buying isn’t automatically the better choice. Renting gives you flexibility to visit different destinations, avoid maintenance responsibilities, and adjust your plans from year to year. Buying makes more sense when you’re confident about the location, expect to use the property regularly, and can comfortably handle the ongoing expenses.
If you’re uncertain, consider renting in the same community for a few seasons before committing to a purchase. You may discover that you love returning to the same place—or that you prefer the freedom to explore somewhere new every summer.
Learn more about the pros and cons with our post: Buying Vs. Renting: How Real Estate is One of Your Best Investments
What Should You Look for When Buying a Beach House?
Beyond the usual considerations of layout, condition, and price, we recommend paying attention to a few details specific to vacation homes:
- Beach access: How far is the walk or bike ride? Is parking available? Are there private access restrictions?
- Outdoor living: Will you actually use the decks, porches, yard, or outdoor shower?
- Storage: Is there room for beach chairs, bikes, toys, and everything else you don’t want to transport each weekend?
- Parking: Can you accommodate family and guests, especially during the summer?
- Year-round usability: Is the home comfortable and practical during colder months?
- Maintenance: Are there exterior materials or features that will require substantial upkeep?
- Rental restrictions: If renting is part of your plan, confirm the rules before purchasing.
- Resale considerations: Think about how the home’s location, accessibility, layout, and ongoing costs may affect future buyers.
And don’t underestimate the value of convenience. A slightly smaller house within walking distance of the beach and restaurants may get much more use than a larger property that requires driving everywhere.
Buying a Beach House While Living in the DC Area
Buying a second home is exciting, but it pays to approach the decision with the same care you’d give any major real estate purchase. Start with your lifestyle goals, understand the full costs, explore financing options, and spend enough time in your preferred destination to know it’s the right fit.
At The Goodhart Group, we help buyers and homeowners throughout Washington, DC, Northern Virginia, and Maryland think through their real estate decisions, including how a second home fits into their longer-term plans. Through our professional network, including Compass agents in coastal markets, we can connect you with experienced local real estate professionals who know your destination. We can also introduce you to knowledgeable lenders who work with second-home and investment-property financing.
Whether you’re dreaming about a place in Bethany Beach, Rehoboth, Ocean City, the Outer Banks, or somewhere entirely different, we’re happy to help you explore your options and connect with the right people.
Get in touch today by filling out the form on this page, by calling 703.362.3221, or by emailing hello@thegoodhartgroup.com.
Looking For Additional Resources?
We’ve got you covered. Click the button below to download our lifestyle, real estate, and area guides.